

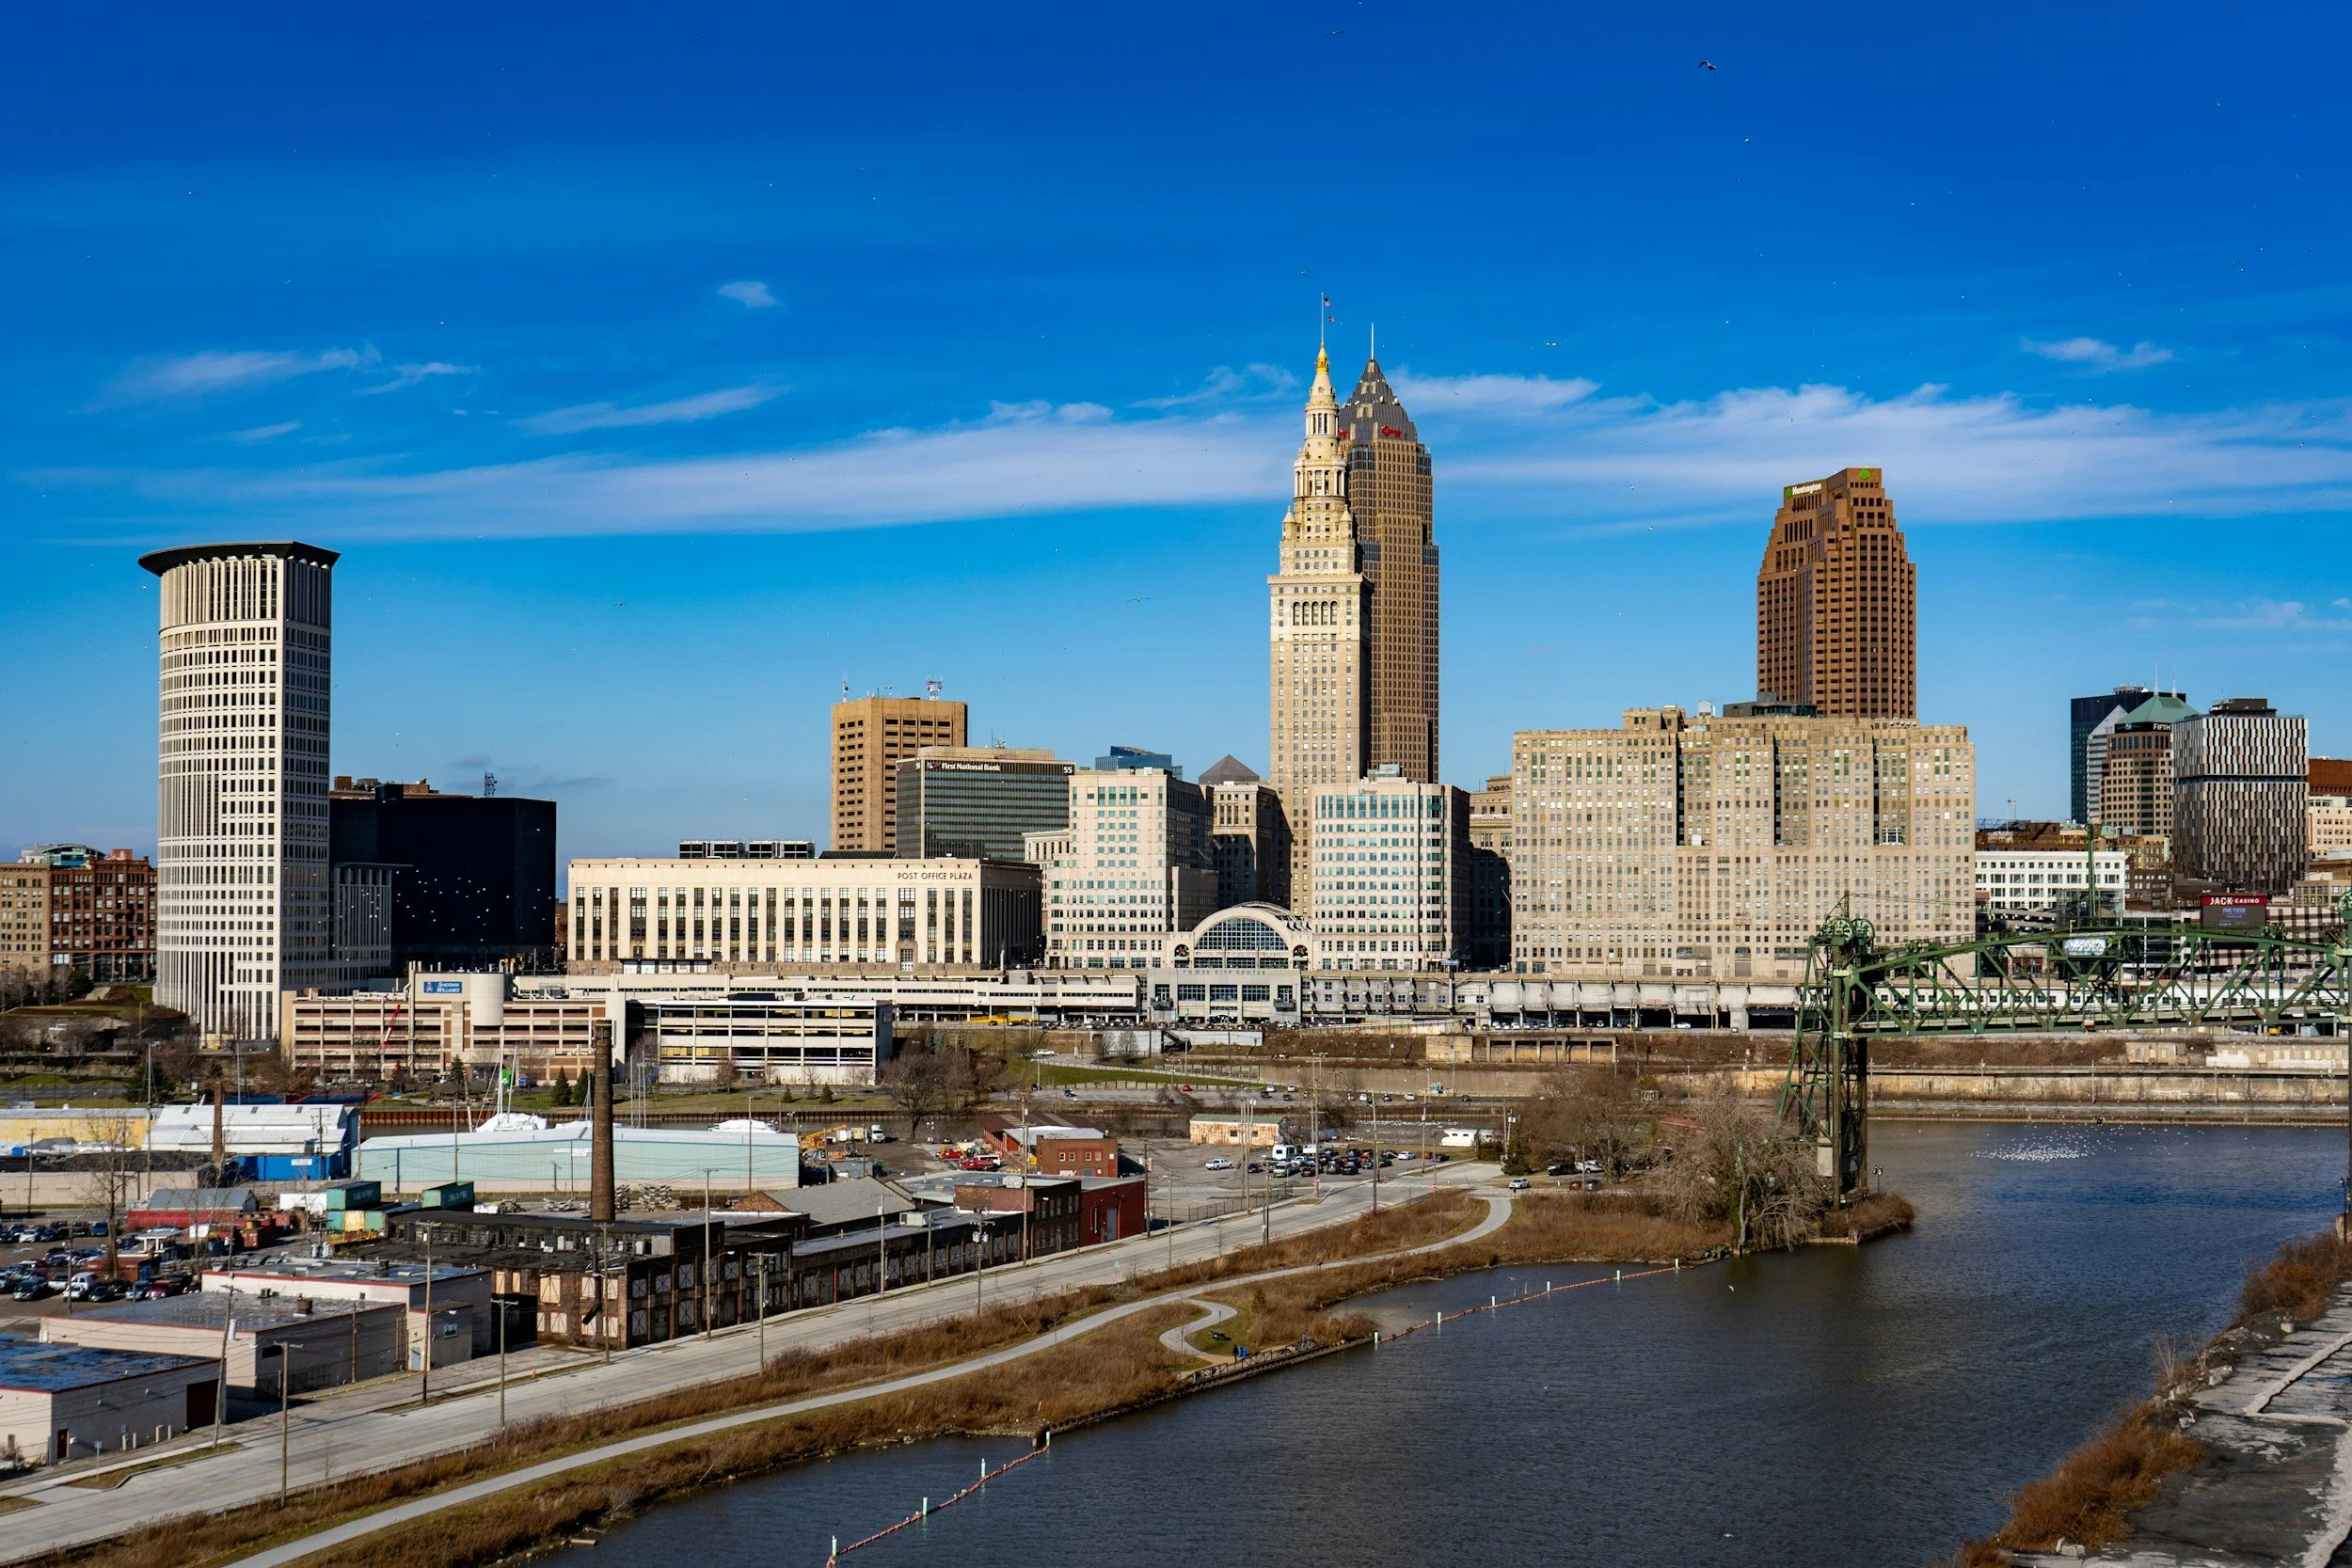
Cleveland is hardly winning the growth-story contest. It added only about 800 jobs last year, yet apartment vacancy remained below 4% because developers have built so little new supply.
Matthews' Q2 2026 market report estimates that the metro added only about 800 net jobs in 2025. Vacancy nevertheless fell to 3.68% in Q2 2026, as rents rose 2.88% year over year. Only 1,430 units were under construction, equal to 0.82% of existing inventory.
For LPs, the lesson reaches beyond Cleveland. Headline growth can attract capital long before the apartment market needs more units. Once construction outruns absorption, strong demographics offer less protection than they appear to on a market overview.
Growth Means Less When Supply Arrives Faster
Austin shows how quickly a compelling growth story can become a difficult leasing market. Years of population gains and corporate expansion drew an extraordinary amount of apartment construction. By Q2 2026, vacancy had improved sharply from its 2024 peak, but it still stood at 12.29%.
Average effective rent was down 3.88% year over year in Q2 even as demand remained healthy. The city absorbed more than 6,300 units during the quarter, but the market was still working through a large stock of vacant apartments created during the building surge. Matthews also added that the construction pipeline has fallen substantially from its 2023 peak, which should improve the balance over time.
Denver sits at a similar point in the cycle. Demand has been strong enough to lift occupancy, yet the earlier supply wave still weighs on revenue. CBRE recorded average rents of $1,764 in Q2 2026, down 5.5% from a year earlier, even after a 1.9% quarterly increase.
More than 6,500 units were absorbed during the quarter, the strongest showing since 2021. CBRE's Q2 2026 figures still show how long a market can take to regain pricing power after heavy deliveries. Good demand helps clear excess inventory, but the units already delivered still have to be absorbed.
Cleveland's Advantage Is Scarcity
Cleveland's numbers look almost inverted. Employment barely grew last year, yet apartments remain tight because developers have added so little relative to the existing base. A limited pipeline leaves owners competing against fewer new lease-ups, which helps preserve occupancy without relying on exceptional demand growth.
Scarcity also changes the burden placed on the business plan. An owner in a lightly supplied market does not need population growth to outrun thousands of new units before rents can move. Modest demand can be enough when the denominator barely changes.
Investment pricing has not fully followed the operating story. Matthews put Cleveland's average cap rate near 8% in Q2, while price per unit remained roughly flat from a year earlier. A market with restrained construction and steady rent growth can therefore offer durable income without requiring a dramatic growth narrative.
Slower-growth markets may offer less upside from rapid rent acceleration, and liquidity can be thinner. Their advantage is a lower hurdle for maintaining occupancy because existing properties are not constantly competing with the next wave of deliveries.
Read the Pipeline Before the Growth Story
Market selection changes once new supply is treated as a first-order variable. Employment growth still matters, but its value depends on how many new households the apartment market must absorb to keep vacancy stable.
A city adding thousands of jobs can disappoint if construction has already priced in even faster growth. Another market may add jobs slowly and still produce firmer rents because developers left the demand base largely untouched.
For LPs, the useful comparison is between the demand a market is producing and the inventory it is asking renters to fill. Current vacancy shows where the balance stands today. The construction pipeline shows where the pressure is likely to move next.
At Gilberti Group, we favor markets where the investment case can work without heroic assumptions about population growth or future rent acceleration. When new construction is restrained, ordinary demand can carry more weight. In the current cycle, that restraint may be one of the most valuable fundamentals a market can offer.
To discuss how Gilberti Group evaluates multifamily markets and supply risk, schedule a conversation with our team.
